Set4LifeAgencyReview: Ownership, Compensation Plan, and Full Business Breakdown
This Set4LifeAgencyReview examines the Florida-based life insurance agency that launched in early 2026. The company sells final expense insurance, indexed universal life (IUL), mortgage protection insurance, and fixed indexed annuities while running an agent recruitment side with MLM-style ranks and bonuses. Readers looking for clear facts on ownership, costs, and how money moves will find the details below.Scamsradar
Part : 1 What the Company Actually Does
Table of Contents
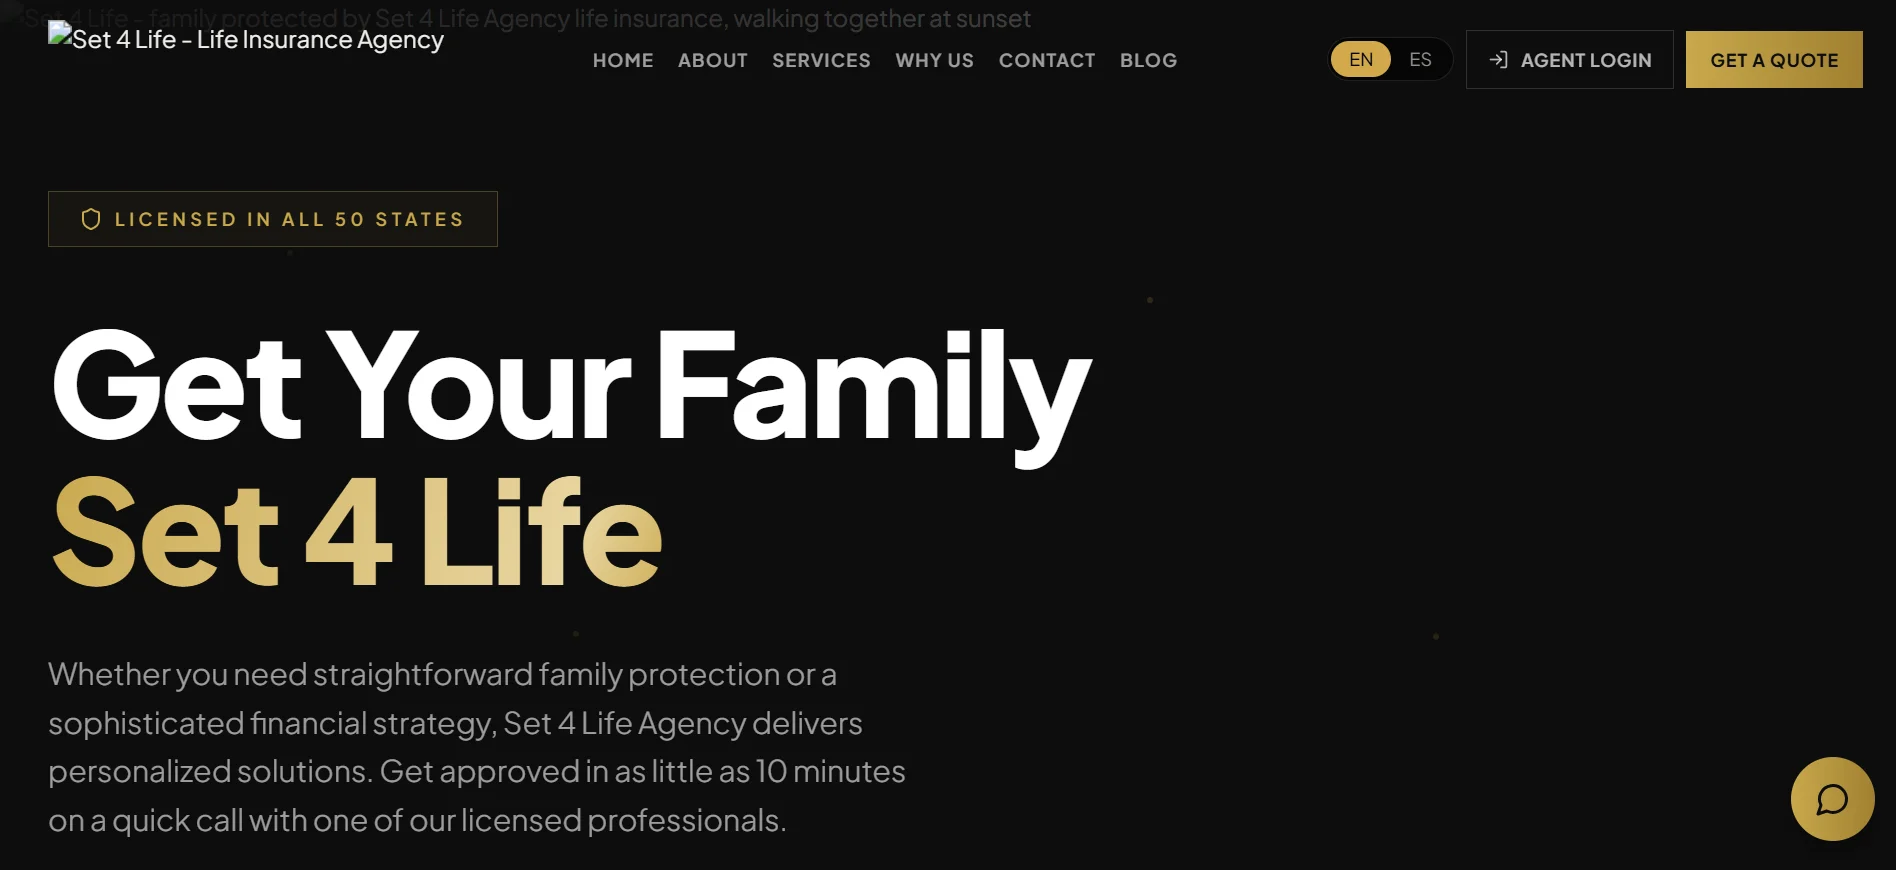
Set 4 Life Agency markets life insurance products to everyday families and higher-net-worth clients. It claims licensing in all 50 states and no-exam policies that can receive approval in about ten minutes. The public site focuses on protection and wealth strategies. Behind the scenes, the real engine is an agent opportunity built around an AI-powered command center that includes scripts, a dialer, CRM tools, and coaching.
The domain appeared in February 2026. The LLC formed on March 18, 2026, at an address in Fort Lauderdale. Contact details listed are admin@set4lifeagency.com and (561) 668-0435. Products come from third-party carriers rather than the agency itself. No public evidence shows a passive investment product that promises fixed high returns to outside capital. Income talk centers on agent commissions and team overrides.
1.1 Ownership and Leadership Profiles
Florida records name Thomas Poulin as the authorized member and registered agent. Poulin presents himself as founder of the first fully AI-powered life insurance brokerage. His earlier path includes Q Sciences, a supplement network-marketing company, followed by Rank Up Academy (coaching aimed at French-speaking Canadians) and RankUp.io, a CRM and automation platform. He also runs Dream Exit Ventures, which focuses on scaling businesses for private-equity sales.
Holton Buggs appears frequently in promotional material. He co-hosted the main May 2026 launch presentation with Ivan Tapia. Buggs has a long network-marketing background that includes Organo Gold, iBuumerang, and crypto-related projects. Florida corporate filings do not list him as an owner. He is a defendant in a CFTC civil enforcement action filed in 2024 involving the Traders Domain commodity pool. The agency alleges more than $280 million in investor losses and names Buggs as a top net-winner who recruited heavily. Asset surrender and injunctions followed. The case remains civil, not a criminal conviction.
Ivan Tapia previously worked with IM Mastery Academy and later Nvisionu. Kristy Fuentes and other agents promote the opportunity on LinkedIn and social channels. Leadership transparency stays limited because the website itself does not display a detailed executive page.
1.2 Rank structure and reported personal commission rates
Rank | Agents Required | Team Premium Required | Reported Commission Rate |
Producer | Base | None | 70% |
Builder | 5 | $25,000 | 80% |
Team Captain | 10 | $50,000 | 90% |
All-Star | 25 | $300,000 | 100% |
MVP | 50 | $500,000 | 115% |
Icon | 100 | $1,000,000 | 120% |
One common example uses a $2,000 annual-premium policy. A 25 percent base plus 75 percent advance yields roughly $375 at entry level. Higher ranks increase the personal rate. Residual renewal rates remain undisclosed.
1.3 Leadership bonuses (unilevel / generational)
Rank | Gen 1 | Gen 2 | Gen 3 | Gen 4 |
Team Captain | 8% | — | — | — |
All-Star | 8% | 3% | — | — |
MVP | 8% | 3% | 4% | — |
Icon | 8% | 3% | 4% | 10% |
These percentages apply to commissionable volume, not necessarily the full customer premium. Exact definitions depend on carrier contracts, product type, and chargebacks.
Part : 2 Promoter costs reported in webinars
- One-time enrollment: about $199
- Monthly promoter fee: $99
- AI marketing / tools: about $997 per month
Combined recurring cost reaches roughly $1,096 per month, or $13,152 per year, before licensing, leads, advertising, taxes, or chargebacks. First-year total with the enrollment fee sits near $13,351.
2.1 Break-Even Math for Everyday Agents
Assume the $375 example holds. Covering the $1,096 monthly fees alone requires about three such policies every month. Annual coverage of the fixed costs needs roughly 36 policies before any other expenses. At higher reported rates the number drops, yet real-world persistency often runs 50–80 percent in the first year and advances can be clawed back on lapses.
A $500,000 annual income claim, if taken at face value, would require $417,000 to $714,000 in relevant premium volume depending on the commission rate applied. At a $2,000 average premium that equals 209 to 358 policies. Recruitment numbers alone do not equal production. Many agents in similar models stay inactive or low-volume.
2.2 Comparison Table: Typical Returns Versus Agent Economics
Avenue | Typical Annual Figure | Nature | Risk Level |
High-yield savings / CD | 3.75–4.5% | Interest | Very low |
10-year Treasury | ~5% | Fixed income | Low |
Rental real estate | 4–12% total | Cash flow + appreciation | Medium |
S&P 500 long-term average | 8–10% | Market returns | Medium |
Set 4 Life agent path | Variable | Commissions after high fixed costs | High |
The agency path is active work, not passive yield. Most new insurance agents in network structures earn far less than their costs after realistic close rates and expenses.
Practical Recommendations
Treat the opportunity as a high-effort insurance sales business with network-marketing overlays, not a passive investment. Verify the LLC and individual agent licenses through state departments of insurance. Request the complete written compensation schedule, carrier contracts, chargeback rules, and any income disclosure that shows median results after all expenses. Calculate personal break-even using realistic close rates and lead costs. Compare products and commissions with established independent agencies that carry lower overhead.
The five-year exit framing and heavy AI marketing claims deserve extra scrutiny. AI tools can improve efficiency, yet they do not create customers or guarantee persistency. Sustainable income still rests on issued, retained policies sold to real buyers outside the agent network.
Set4lifeagency Review
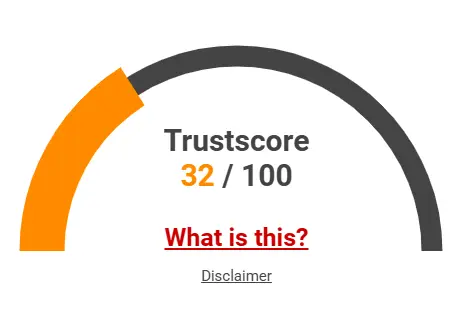
A website’s trust score is an important indicator of its Set4lifeagency icludes low web traffic, negative user feedback, potential phishing risks, undisclosed ownership, unclear hosting details, and weak SSL encryption.
With such a poor trust score, the likelihood of fraud, data breaches, or other security issues is much higher. It is crucial to carefully assess these warning signs before engaging with Set4lifeagency Similar platform.
Positive Highlights
- We found a valid SSL certificate
- DNSFilter labels this site as safe
Negative Highlights
- The Tranco rank (how much traffic) is rather low.
- The age of this site is (very) young.
Frequently Asked Questions About Set4lifeagency
This section answers key questions about Set4lifeagency concerns, and highlights issues related to the platform’s legitimacy.
Set4LifeAgency appears to operate as an insurance agency, but its compensation structure and income claims should be independently verified before joining.
The reported plan combines insurance sales commissions with team-based bonuses, rank requirements, and leadership incentives.
Reported promotional materials mention an initial fee and recurring costs, including charges for AI and marketing tools.
Set4LifeAgency promotes life insurance, final-expense insurance, mortgage protection, indexed universal life, and fixed indexed annuities.
No. Everstead Review concerns a different platform and should not be confused with Set4LifeAgency.
Other Infromation:
WHOIS data : Hidden
Owner : REDACTED FOR PRIVACY
Country: US
WHOIS Registration Date :2026-02-04
WHOIS Last Update:2026-02-04
WHOIS Renew Date:2029-02-04
Website: Set4lifeagency
Title :Set4lifeagency
Reviews:
There are no reviews yet. Be the first one to write one.