CryptolaneReview: Ownership, Compensation Plan, and Risk Analysis for the Crypto Trading Platform
This CryptolaneReview examines the trading platform that markets itself as a digital exchange for spot trading, futures, staking, lending, swaps, and passive income tools. The review focuses on ownership details, the compensation structure, and key risk factors so readers can form their own view. Information comes from public records, domain data, and third-party reports available in mid-to-late August 2026.
The platform presents a clean interface with market tables and earn features. Yet the domain is only weeks old, ownership claims raise questions, and the yield figures lack independent proof. Below is a clear breakdown of what is known and what remains unverified.ScamsRadar
Part : 1 What Is Known About Ownership and Company Background
Table of Contents
Public materials on the site name DIGITALK DASH LIMITED as the operator. This is a real UK company.
- Company number: 14018271
- Incorporated: 1 April 2022
- Status: Active
- Registered office: 167–169 Great Portland Street, London
- SIC code: 70229 (management consultancy activities other than financial management)
- Director and person with significant control: Adekunle Olukayode Oladimeji (75%+ shares and voting rights)
Companies House confirms these facts. The firm is classed as a micro company. Recent filings show very small figures: total assets around £3.68k in 2024, liabilities higher, and negative net assets near £11–13k. Employee numbers appear limited to one or two.
A German law firm has publicly alleged that the platform may be using the DIGITALK DASH name without proper authority. This remains an allegation, not a court finding. No public record clearly links Oladimeji himself to day-to-day operation of the exchange. Searches turn up no verified criminal convictions, Ponzi history, or MLM records tied to him or the company in connection with this platform.
Several other crypto-related sites have also displayed the same UK company number. This pattern raises a simple question: why does one small consultancy appear linked online to so many exchange brands? No contracts, licences, or custody documents have been published to answer it.
WHOIS data for the domain stays privacy-protected. Registration date is 14 July 2026. By late August 2026 the site is roughly six weeks old. No clear physical address, regulatory licence from bodies such as the FCA or equivalent, or audited financial statements appear in public sources.
1.1 Compensation Plan and Referral Structure
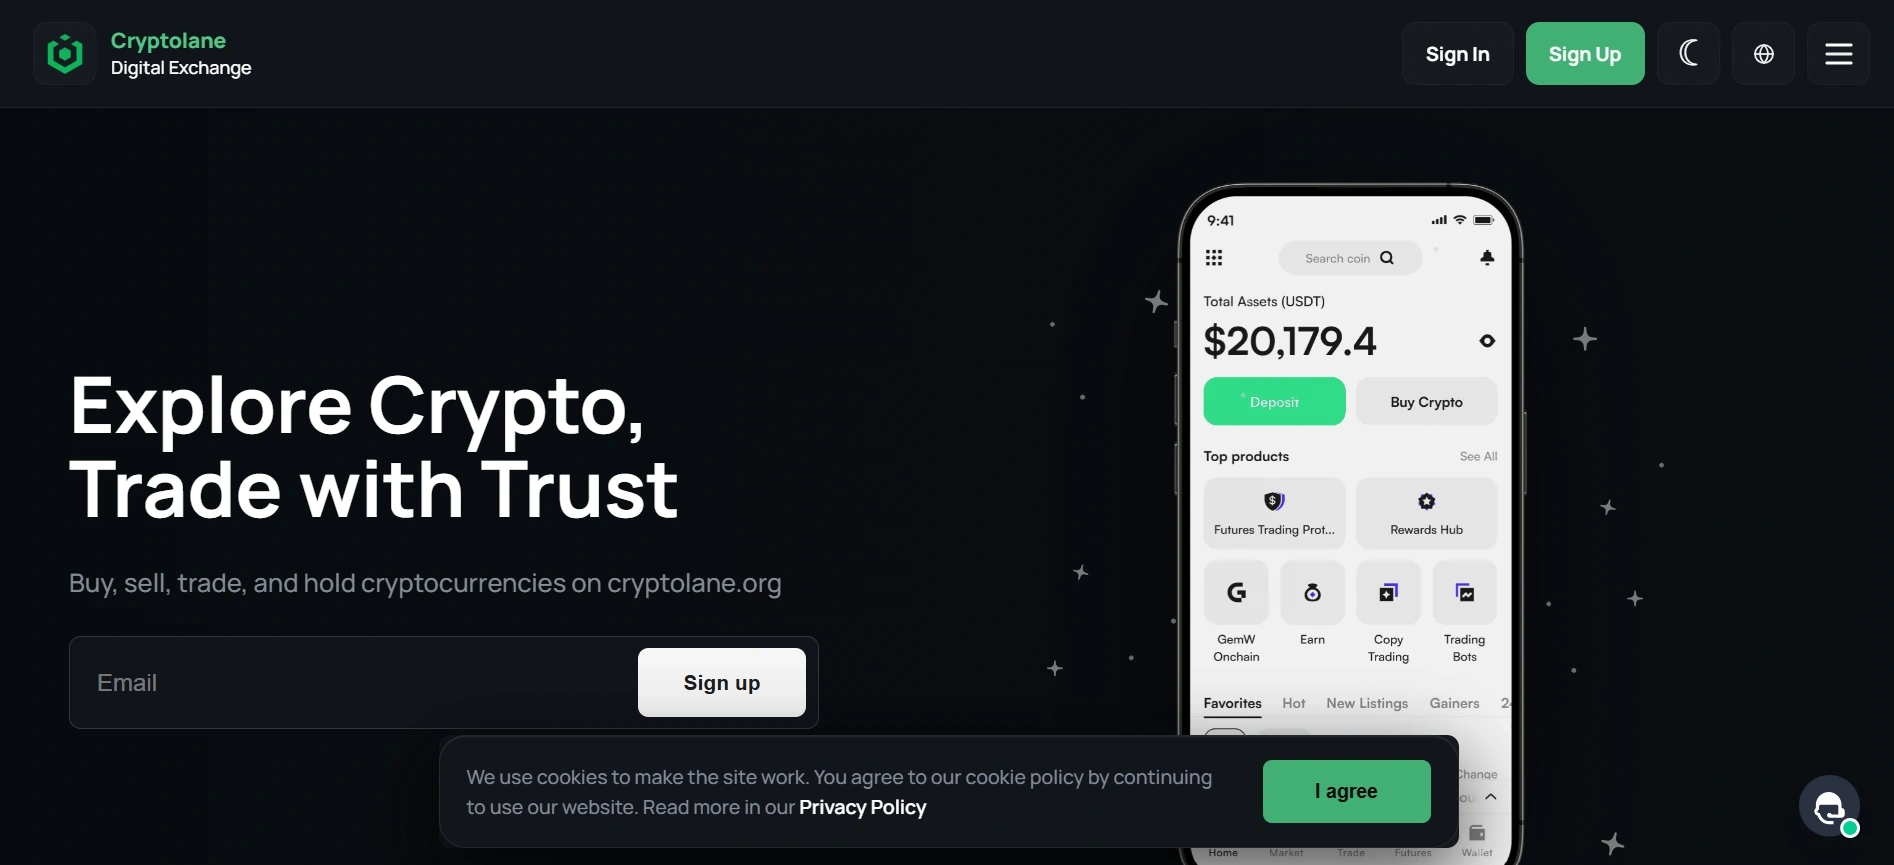
The platform confirms a referral system. Users receive personal links and invitation codes. Eligible activity by new sign-ups can generate rewards or commissions. The signup form includes fields for promo and invitation codes.
This is best described as a standard referral or affiliate model:
- Existing user shares a personal link
- New user registers and completes eligible activity
- Referrer receives a reward
No public document shows left/right binary legs, generation percentages, matrix sizes, pairing rules, spillover, matching bonuses, rank qualifications, or carry-forward volume. Claims of a full multi-level marketing plan therefore lack supporting evidence. Commission rates themselves are not disclosed in clear detail on public pages.
Lending rates are advertised in a range from roughly 0.3% to 24.85%. The site does not state whether the higher figure is annual, monthly, or promotional. Staking language sometimes suggests daily profits and principal protection. Real blockchain staking carries price risk, validator risk, and possible lock-up periods. Guarantees of safety require stronger proof than marketing text.
A basic sustainability check helps illustrate the numbers. Suppose the platform holds $10 million in customer capital and pays an average 24.85% annual return. Interest owed would total about $2.485 million per year before any operating costs, referral payouts, or losses. If trading fees supplied the money at a typical 0.10% rate, the exchange would need roughly $2.485 billion in annual volume—or around $6.8 million per day—just to cover interest. Real costs would push the required volume higher. No independent trading volume, loan book, or reserve data has been published to show this activity exists.
1.2 Compare typical realistic yields:
Asset Class | Typical Annual Range (2026) | Notes |
Bank savings / short Treasuries | 1–4% | Low risk |
Long-term real estate | 7–12% | Includes rent + appreciation |
Legitimate exchange staking / earn | 1.5–8% (higher for promos) | Varies by asset and lock-up |
High-risk DeFi | Temporary double digits | Smart-contract and IL risk |
Consistent multi-hundred-percent compounded returns across all users without transparent external revenue fall outside normal market ranges.
Part : 2 Traffic, Security, and Public Perception
Major ranking lists show negligible traffic. Automated scanners give mixed but cautious scores. One service rated the main domain around 70/100 with a single phishing flag; related domains scored far lower and appeared on multiple blacklists. SSL is present via Cloudflare, but it is domain-validated only. No evidence of advanced audits, cold-storage proofs, or penetration-test reports appears publicly.
Customer-support claims stay generic. Reports from similar platforms describe delayed replies once withdrawals are requested and requests for extra “compliance” or node fees. Public review history is almost empty. Social promotion seems limited to private messaging channels rather than verified high-follower accounts.
Some pages have returned 404 errors, adding to questions about operational continuity.
2.1 Key Risk Indicators in Plain Language
- Domain age measured in weeks, not year
- Ownership claims that do not fully match independent company records
- High advertised yields without published revenue sources or reserves
- Confirmed referral incentives that reward bringing in new deposits
- No visible regulatory licences
- Limited independent reputation and low public traffic
These points do not prove fraud. They do show that independent verification is currently thin.
Practical Steps for Anyone Considering the Platform
Check the UK Companies House record for DIGITALK DASH LIMITED yourself. Ask the platform for wallet addresses that can be verified on-chain, proof of reserves, audited statements, and a clear written explanation of how lending and staking yields are generated. Prefer platforms with long operating histories, published licences, and transparent custody arrangements.
If funds are already deposited, keep full records of every transaction and communication. Avoid sending extra fees requested solely to “release” a withdrawal.
Crypto Lane Review
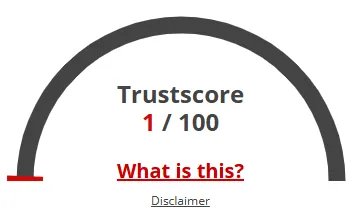
A website’s trust score is an important indicator of its Crypto Lane includes low web traffic, negative user feedback, potential phishing risks, undisclosed ownership, unclear hosting details, and weak SSL encryption.
With such a poor trust score, the likelihood of fraud, data breaches, or other security issues is much higher. It is crucial to carefully assess these warning signs before engaging with a Crypto Lane Similar platform.
Positive Highlights
- We found a valid SSL certificate
- DNSFilter labels this site as safe
Negative Highlights
- The Tranco rank (how much traffic) is rather low.
- The age of this site is (very) young.
Frequently Asked Questions About Crypto Lane
CryptoLane has several transparency and investment-risk concerns that require careful research.
It claims to generate profits through crypto-related investment and trading activities.
Risks include unclear ownership, high-return claims, and potential withdrawal problems.
Risks include unclear ownership, high-return claims, and potential withdrawal problems.
Check its registration, leadership, revenue sources, withdrawals, and investment claims.
No. Everstead Review is separate and should not be used to assess CryptoLane.
Other Infromation:
WHOIS data : Hidden
Owner : REDACTED FOR PRIVACY
Country: US
WHOIS Registration Date:2026-07-14
WHOIS Last Update:2026-07-14
WHOIS Renew Date:2027-07-14
Website: Crypto Lane
Title : Crypto Lane
Reviews:
There are no reviews yet. Be the first one to write one.