
Ergo Proxy Review 2026: Ownership, Compensation Plan, and Risk Assessment
This Ergo Proxy review examines the platform’s structure, ownership records, and compensation mechanics as of August 2026. The site combines proxy services with deposits, referral rewards, ranks, and holding-period bonuses. Readers seeking clear facts on the model will find the key details below. Scams Radar
Table of Contents
Part : 1 Company Registration and Director Background
ERGO PROXY LIMITED appears in UK Companies House records under number SC858817. The firm was incorporated on 12 August 2025. Its registered office is listed at 5 South Charlotte Street, Edinburgh, EH2 4AN. The stated activity is management consultancy outside financial management.
The sole listed director is Eduards Doroskevics. Records show he was born in September 1989, holds Latvian nationality, and resides in Scotland. He was appointed on the incorporation date. Public filings also link him to an earlier company, SATORI-ENGINEERING LTD (SC519278), incorporated in 2015 and dissolved in 2020. That earlier firm operated under an engineering classification. No verified public records of criminal convictions, FCA enforcement actions, or prior investment-scheme operations involving the director were located in the available sources.
The Edinburgh address is used by many other entities, including office-service providers. A UK company registration confirms legal existence but does not equal financial regulation or deposit protection. No indexed FCA authorisation for investment activities was found for the company at the time of review.
1.1 How the Platform Describes Its Model
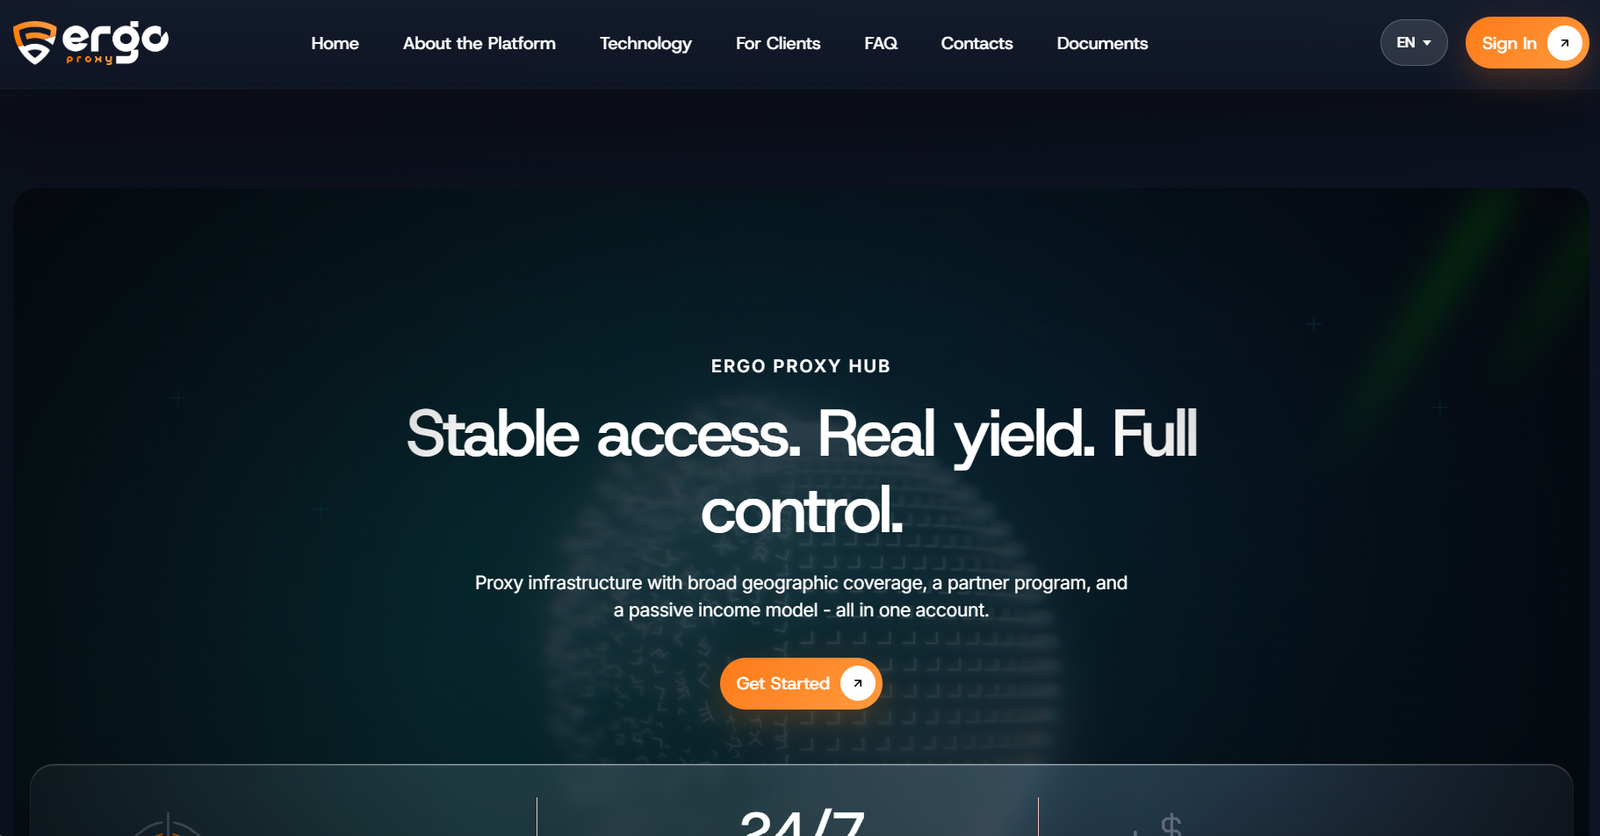
The platform presents three linked parts. Users can select proxy types and locations. They can also invite partners, build ranks, and receive team bonuses. Separately, deposits generate passive income that can rise with longer holding periods. The FAQ states that proxy use is not required to earn the deposit income.
This hybrid design is the core point for any assessment. A proxy business can earn fees from actual usage. Deposit returns and network rewards create ongoing payment obligations that must be funded from somewhere.
1.2 Compensation Plan Details
Public material and promotional posts describe the following elements.
- First-line subscription commission: 30 percent. On a $100 subscription, the direct referrer can receive $30.
- Holding bonuses that increase over time:
- Months 1–3: +1 percent per month
- Months 4–6: +2 percent per month
- Months 7–12: +5 percent per month
- 12+ months: +7 percent per month
Withdrawing a deposit resets the holding period. Active subscriptions may improve yield terms. A 250 USDT Quick Start Bonus has been advertised for users who open a first deposit and reach the initial partner rank within a set window (often 14 days).
Ranks, network depth, team activity, and structure-development bonuses are also referenced. Exact percentages beyond the first-line 30 percent and the holding schedule are not fully published on public pages. Further details appear available only inside a registered account.
Part : 2 Simple Mathematics of the Holding Schedule
A 7 percent monthly rate produces the following results on a $1,000 deposit:
- Simple monthly credit: $70
- Simple annual total: $840 (84 percent)
- Monthly compounding for one year: roughly $2,252 (about 125 percent growth)
On a larger scale the numbers grow quickly. A $10 million deposit pool at 7 percent monthly would require $700,000 each month, or $8.4 million in a simple annual year, before commissions, infrastructure costs, staff, marketing, taxes, or principal withdrawals. These figures are stress tests based on advertised rates. They do not claim to state the platform’s actual liabilities.
2.1 Money-Flow Considerations
A sustainable system needs external revenue or verified investment profit large enough to cover yields, commissions, bonuses, operating costs, and withdrawals. New deposits are capital inflows, not operating profit. If proxy revenue alone cannot meet the obligations, continued inflows become necessary to keep payments flowing.
The platform accepts cryptocurrency only. No bank cards are used. Withdrawals face a minimum activity period (commonly 14 days) and processing times that can reach seven days, or shorter for higher subscription tiers. No additional identity verification is currently required according to the FAQ.
2.2 Transparency Gaps
Publicly available information does not include audited financial statements, total deposit liabilities, actual proxy-service revenue, net margins, proof of reserves, or a complete multi-level commission schedule. First accounts for the UK company are not due until 2027. Wallet addresses and on-chain flow data are not published for independent review.
Part : 3 Summary of Observed Factors
Documented elements
- Active UK limited company and named director
- Published legal pages (AML, terms, privacy, risk disclosure)
- Functional website with HTTPS
- Clear description of proxy selection tools
- Stated 30 percent first-line commission and holding-bonus schedule
Areas requiring further evidence
- Independently verified source of the passive yields
- Complete rank and multi-level percentage tables
- Audited revenue versus deposit obligations
- Proof that returns can continue without ongoing new capital
3.1 Practical Guidance
Anyone considering participation should request documentary answers on total deposits, outstanding liabilities, external customer revenue, wallet custody, and the exact yield formula before sending funds. Successful dashboard balances or early withdrawals do not prove long-term liquidity. Crypto transfers are generally irreversible.
Compare any advertised rates with regulated benchmarks. Ordinary bank savings, property income, and established staking products typically sit far below 84 percent simple annual or 125 percent compounded figures. High advertised yields require correspondingly high and transparent economic activity to remain solvent.
Conclusion
This Ergo Proxy review shows a young UK company with an identifiable director and a stated proxy product. At the same time, the deposit-plus-network model carries substantial financial demands. The combination of rising holding bonuses, referral commissions, rank incentives, and limited public financial disclosure places the passive-income side in the high-due-diligence category. Treat any deposit as speculative capital that can be lost in full. Verify every claim independently, examine current Companies House and FCA records, and never commit funds you cannot afford to lose.
Ergo. Review
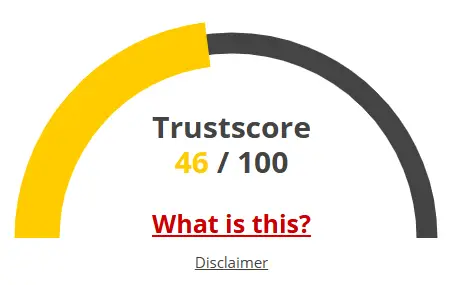
A website’s trust score is an important indicator of its reliability Ergo. includes low web traffic, negative user feedback, potential phishing risks, undisclosed ownership, unclear hosting details, and weak SSL encryption.
With such a poor trust score, the likelihood of fraud, data breaches, or other security issues is much higher. It is crucial to carefully assess these warning signs before engaging with a Ergo.Similar platform.
Positive Highlights
- We found a valid SSL certificate
- DNSFilter labels this site as safe
Negative Highlights
- The Tranco rank (how much traffic) is rather low.
- The age of this site is (very) young.
Frequently Asked Questions About Ergo.
This section answers key questions about Ergo. clarifies points, addresses concerns, and highlights issues related to the platform’s legitimacy.
Ergo Proxy has several transparency and investment-risk concerns.
It appears to use an investment and referral-based model.
Risks include unclear ownership, withdrawals, and unsustainable returns.
Guaranteed or unusually high returns should be treated as a red flag.
There is no clear evidence confirming a connection.
Other Infromation:
WHOIS Registration Date: 2026-03-23
WHOIS Last Update: 2026-06-02
WHOIS Renew Date: 2027-03-23
Website: Ergo.
Reviews:
There are no reviews yet. Be the first one to write one.